


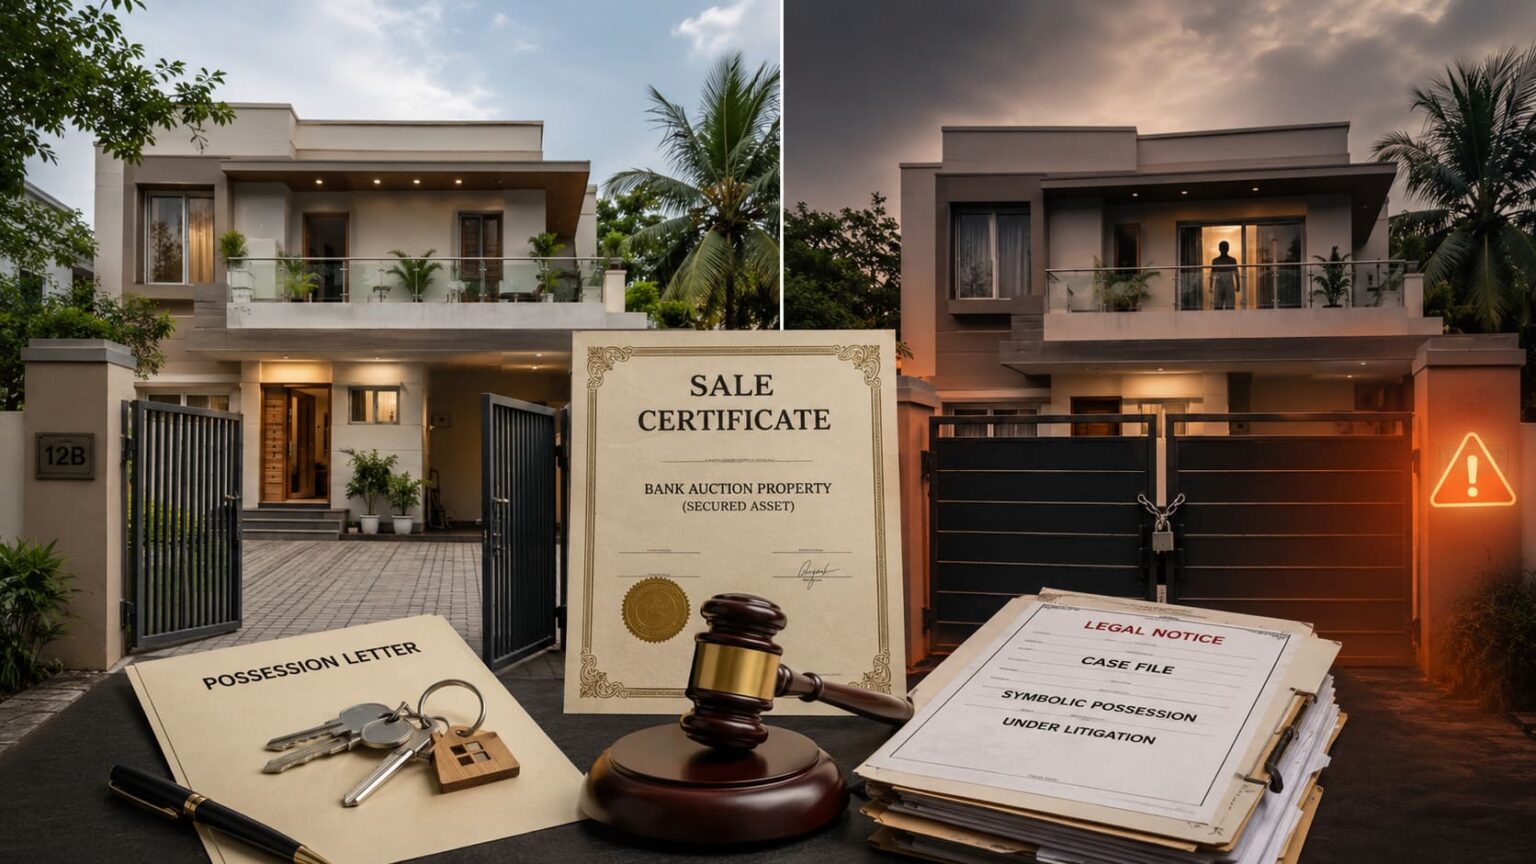
Buying a property through a bank auction does not end when you become the highest bidder. Winning the auction is only the beginning of the ownership-transfer process. The purchaser must complete the payment, obtain the Sale Certificate, deal with registration and pending dues, and secure physical possession of the property.
Understanding these post-auction steps is especially important when buying property under the SARFAESI Act, as auction properties are usually sold under specific conditions and may carry possession or documentation risks.
Pay 25% of the Auction Amount
Once the bank declares a bidder successful, the purchaser must normally deposit 25% of the sale price, including the Earnest Money Deposit already paid, within the period specified by the bank.
The remaining 75% must generally be paid within the deadline mentioned in the auction notice or within any extension formally granted by the secured creditor.
Failure to pay within the permitted period can lead to cancellation of the sale and forfeiture of the amount already deposited. Buyers must therefore arrange the required funds before participating in the auction.
Obtain the Sale Certificate from the Bank
After the entire auction amount is paid and the sale is confirmed, the bank’s Authorised Officer issues a Sale Certificate in favour of the successful bidder.
The Sale Certificate records essential details such as:
- Name of the auction purchaser
- Description of the property
- Final auction price
- Date of sale
- Confirmation that the purchase amount has been paid
Under Rule 9 of the Security Interest (Enforcement) Rules, the Authorised Officer issues the certificate after the sale is confirmed and the purchase price is paid.
The certificate is generally issued in the name of the person or entity that participated in the auction and submitted the required KYC documents.
The Sale Certificate is generally issued in the name of the successful bidder. A bidder who later wishes to transfer the property to another person may have to complete a separate registered transfer, subject to applicable stamp duty, registration charges and legal requirements.
Complete Stamp Duty and Registration Formalities
The purchaser must next approach the appropriate Sub-Registrar Office and complete the applicable registration formalities.
Stamp duty and registration charges can depend on:
- The state in which the property is located
- The auction value
- The property’s guideline or market value
- Whether the auction was conducted by a bank, DRT or another authority
- Current state registration rules and departmental circulars
The buyer should obtain a written calculation from the jurisdictional Sub-Registrar instead of relying only on figures published in the auction listing or on third-party websites.
In Tamil Nadu, registering a bank-auction property may generally attract 7% stamp duty and 2% registration fee—around 9% in total—calculated on the applicable property value, subject to the document type and current Sub-Registrar assessment.
The original Sale Certificate, auction notice, payment receipts, confirmation letter, bank authorisation documents and the purchaser’s identity documents may be required during the process.
Check Whether Possession Is Physical or Symbolic
One of the most important issues after buying an auction property is its possession status.
Physical possession
Physical possession means the bank already controls the property and normally has access to it. The premises may be vacant, sealed or under the direct custody of the bank.
In such cases, the purchaser may receive possession after:
- Paying the complete sale amount
- Receiving the Sale Certificate
- Completing the required documentation
- Signing a possession-handover record
However, buyers must still inspect the property and obtain the keys and written possession confirmation from the bank.
Symbolic possession
Symbolic possession means the bank has legally initiated possession proceedings, but the borrower, tenant or another occupant may still be physically occupying the property.
The bank may have to approach the District Magistrate or Chief Metropolitan Magistrate under Section 14 of the SARFAESI Act to obtain assistance in taking physical possession.
Purchasing a property under symbolic possession can therefore involve delays. The buyer may hold a Sale Certificate but still be unable to immediately enter, use, rent or renovate the property.
Before bidding, buyers should confirm in writing whether the bank promises to deliver vacant physical possession or whether the purchaser is expected to deal with the occupant.
Take Formal Handover of the Property
The buyer should not treat the Sale Certificate alone as proof that physical possession has been delivered.
At the time of handover, obtain:
- Possession letter or handover certificate
- Property keys
- Photographs and videos of the property’s condition
- Electricity and water meter readings
- Details of fixtures included in the sale
- Records of any locks or seals removed
- Copies of available original title documents
The possession letter should mention the date on which the bank handed over the property and the condition in which it was delivered.
If the property is occupied, the purchaser should avoid attempting forcible eviction. Possession must be obtained through the bank or through the legally prescribed process.
Verify Pending Property Dues
Bank-auction properties are commonly sold on an “as is where is,” “as is what is” and “whatever there is” basis.
These clauses mean the buyer accepts the property in its current physical and legal condition as per auction terms.
After purchase, the buyer may face pending dues such as property tax, water and electricity bills, maintenance charges, sewerage fees, development authority dues, lease rent, or other statutory payments.
However, responsibility for past dues varies based on the type of charge, applicable law, auction conditions, and whether the liability is attached to the property or the previous owner.
The buyer should obtain written confirmations from all authorities and seek legal advice before clearing any disputed old dues.
Transfer Revenue and Municipal Records
After completing the Sale Certificate and registration process, the purchaser should apply to update the property records.
Depending on the property and state, this may include:
- Patta or revenue-record mutation
- Municipal property-tax name transfer
- Electricity service-name transfer
- Water and sewerage connection transfer
- Apartment association membership update
- Planning or development authority records
- Leasehold or allotment records, where applicable
Mutation does not independently create title, but it updates the government’s revenue and tax records to show the new owner.
Keep certified copies of the Sale Certificate, registration receipt, possession letter and payment records while making these applications.
Examine the Original Property Documents
The purchaser should collect all available original documents held by the bank, including:
- Previous title deeds
- Parent documents
- Mortgage documents
- Encumbrance-related papers
- Approved building plan
- Planning permission
- Completion or occupancy certificate, where applicable
- Property-tax receipts
- Patta or revenue documents
- Apartment undivided-share documents
- Society or association records
Banks may possess only the documents deposited by the borrower. The availability of original documents does not automatically confirm that every planning, construction or title issue has been resolved.
A lawyer should compare the documents received with the property description in the auction notice and Sale Certificate.
Obtain an Updated Encumbrance Certificate
After registration, obtain an updated Encumbrance Certificate covering the relevant period.
Check whether it reflects:
- The earlier owner’s title
- The bank mortgage
- The auction sale or Sale Certificate
- Any attachments, court orders or competing transactions
An Encumbrance Certificate alone cannot reveal every possible dispute, unregistered claim, tenancy or statutory liability. It must be reviewed along with the title deeds, court searches, revenue records and physical inspection.
What If the Bank Delays Possession?
If the bank sold the property with an assurance of physical or vacant possession but fails to deliver it, the purchaser should first send a written representation seeking:
- Current possession status
- Details of action taken under Section 14
- A definite handover schedule
- Copies of relevant orders or proceedings
If the problem continues, the purchaser may need to issue a legal notice and pursue the remedy available under the auction terms and applicable law.
Refund, interest or compensation is not automatic in every delayed-possession case. The buyer’s rights depend on the sale notice, representations made by the bank, possession status disclosed before the auction and the surrounding facts.
Can the Former Owner Challenge the Auction?
The borrower or another affected person may challenge measures taken by the secured creditor before the Debt Recovery Tribunal under the remedies provided by the SARFAESI Act.
A challenge does not automatically cancel every completed auction. Its effect depends on the tribunal or court’s orders and whether the bank followed the mandatory auction procedure.
The purchaser should therefore continue monitoring any pending DRT, High Court, insolvency or civil proceedings connected with the property even after receiving the Sale Certificate.
Final Checklist After Buying a Bank-Auction Property
After winning the auction, the purchaser should:
- Pay the auction amount within the deadline.
- Obtain payment acknowledgements from the bank.
- Receive the original Sale Certificate.
- Complete the applicable stamp-duty and registration process.
- Obtain a written possession letter and property keys.
- Verify whether the property is vacant or occupied.
- Collect all original documents available with the bank.
- Check property tax, utility and association dues.
- Update revenue, municipal and utility records.
- Obtain an updated Encumbrance Certificate.
- Inspect the property and document its condition.
- Continue monitoring pending legal proceedings.
Conclusion
A bank-auction property may be available below the prevailing market price, but the transaction requires more than simply winning the bid. The purchaser must complete the payment, secure the Sale Certificate, comply with registration requirements, obtain physical possession and address outstanding documentation or dues.
The biggest risk is usually not the auction payment itself but what comes afterward—particularly where the property is occupied, sold under symbolic possession or affected by pending claims.
Buyers should verify the auction notice, title records, possession status, statutory dues and pending litigation before bidding. Legal and technical due diligence remains essential even when the seller is a bank.
Disclaimer: This article is for general informational purposes and does not constitute legal advice. Auction conditions, possession procedures, taxes and registration requirements can vary depending on the property, state, bank and applicable orders.