

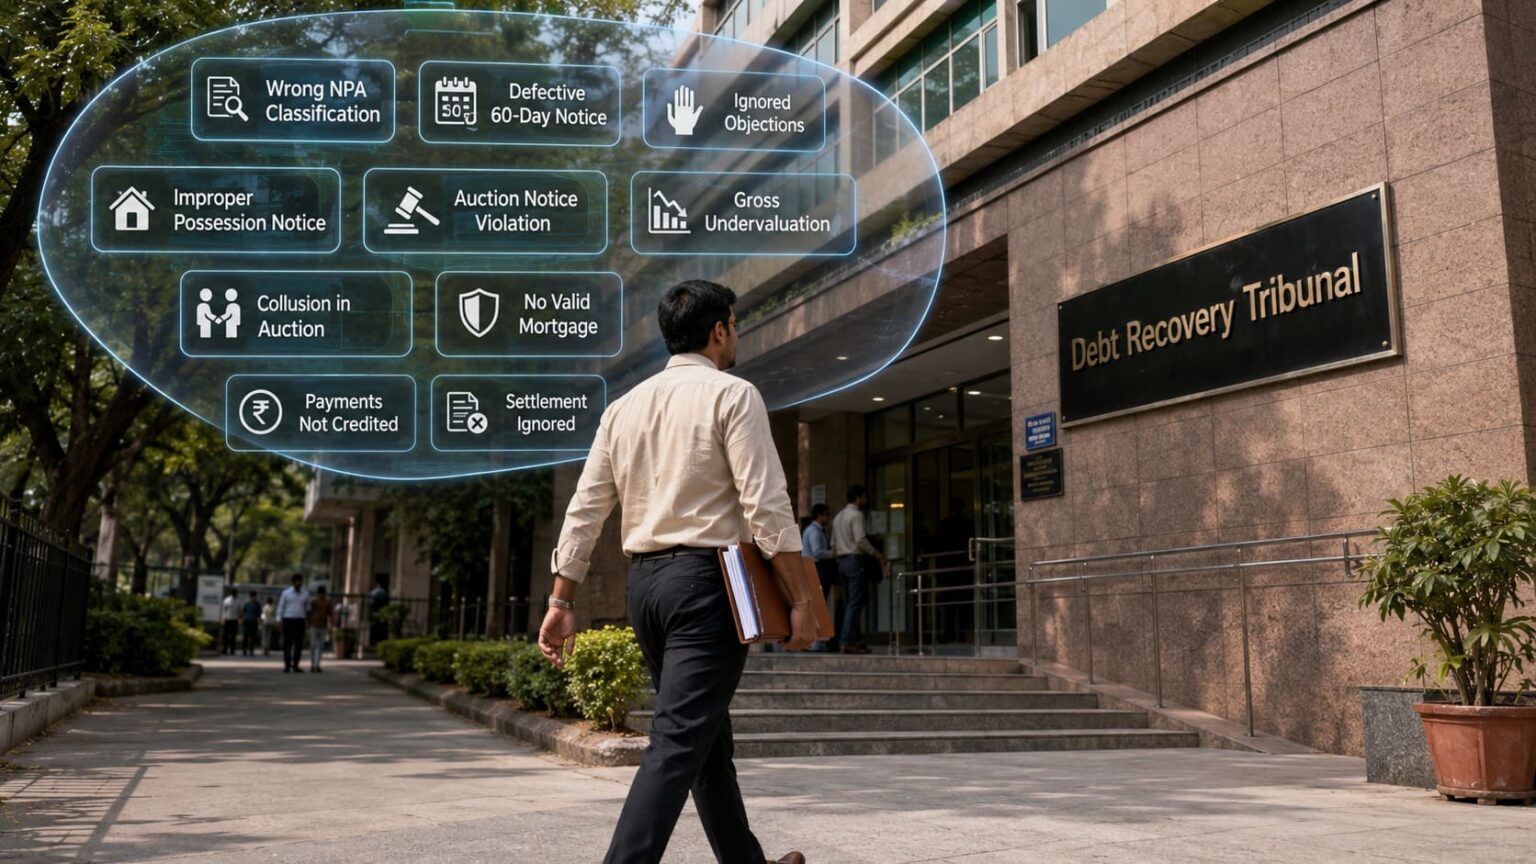
The SARFAESI Act allows banks and financial institutions to take possession of mortgaged properties and sell them when secured loans remain unpaid. However, a bank cannot auction a property without following the procedure prescribed under the Act and the Security Interest (Enforcement) Rules, 2002.
A borrower, guarantor, property owner or any other affected person can approach the Debt Recovery Tribunal under Section 17 of the SARFAESI Act when the bank takes measures such as possession or auction of the secured property. The application must generally be filed within 45 days of the challenged action.
Major Grounds for Challenging a SARFAESI Auction
Incorrect NPA Classification
SARFAESI proceedings can be initiated only after the secured loan has been classified as a 1Non-Performing Asset in accordance with applicable RBI norms.
The owner may challenge the proceedings if payments were ignored, the overdue period was calculated incorrectly, the outstanding amount was wrong or the bank classified the account as an NPA despite the loan being regularised.
Defective Demand Notice
Before taking possession, the bank must issue a notice under Section 13(2), giving the borrower 60 days to repay the dues.
The proceedings may be questioned if the notice was not properly served, contained a materially incorrect amount, wrongly described the property or did not provide the required period.
Failure to Consider the Borrower’s Objections
A borrower can submit objections against the demand notice. Under Section 13(3A), the bank must consider them and communicate reasons when they are rejected.
In ITC Limited v. Blue Coast Hotels Limited, the Supreme Court stressed that banks must meaningfully consider the borrower’s representation instead of treating the process as an empty formality.
Improper Possession or Auction Notice
The auction may be challenged where the bank failed to:
- serve the possession or sale notice properly;
- publish the auction notice in the required newspapers;
- provide the mandatory notice period;
- correctly describe the property;
- disclose the reserve price and auction conditions; or
- issue a fresh notice when required.
In Mathew Varghese v. M. Amritha Kumar, the Supreme Court held that banks must strictly follow the statutory sale procedure and provide the borrower with the required notice before selling the property.
Gross Undervaluation of the Property
Before an auction, the bank must obtain a valuation from an approved valuer and fix a reserve price.
An owner may approach the DRT if the valuation is outdated, important property features were ignored, the reserve price was arbitrarily reduced or the property was sold substantially below its genuine market value.
A low sale price alone may not invalidate an auction. The owner must normally demonstrate serious valuation defects, procedural violations, collusion or lack of genuine competition.
In a Kodagu plantation auction case, the Karnataka High Court questioned how a 39-acre estate worth about ₹3.12 crore was valued at ₹61 lakh and sold for ₹99 lakh, also raising concerns about the valuer’s qualifications. The case highlights that major undervaluation and improper valuation can be grounds to challenge a SARFAESI auction, though it is still under judicial scrutiny.
Collusion or Manipulation During Auction
The auction can be questioned if genuine bidders were prevented from participating, bidding records were manipulated, the successful bidder was given special treatment or bank officials colluded to sell the property at an artificially low price.
Such allegations must be supported by documents and not merely suspicion.
Auction Purchaser Failed to Make Payment Properly
The successful bidder must pay the deposit and balance auction amount within the period prescribed under the Rules.
The owner may challenge the sale if the bank illegally extended the payment deadline, accepted delayed payment without authority or issued the sale certificate before receiving the full consideration.
In Agarwal Tracom Pvt. Ltd. v. Punjab National Bank, the Supreme Court recognised that even an auction purchaser affected by measures taken under the SARFAESI Rules may approach the DRT under Section 17.
Property Was Not Validly Mortgaged
A third-party property owner may challenge the auction where:
- no valid mortgage was created;
- the owner never signed the mortgage documents;
- documents were forged;
- the person creating the mortgage had no authority;
- the bank auctioned a property different from the secured property; or
- the mortgage covered only a portion of the property.
Section 17 is available to “any person” affected by the bank’s enforcement action and is not restricted only to the borrower.
Bank Ignored Full Payment or Settlement
An auction may also be challenged if the borrower had already discharged the loan, complied with an accepted settlement or made payments that the bank failed to credit.
However, a mere request for more time or an unaccepted settlement proposal will not usually stop a lawful auction.
Borrower’s Right to Redeem the Property
Under the amended Section 13(8), the borrower must tender the entire outstanding amount, together with applicable costs and expenses, before publication of the sale notice to exercise the statutory 2right of redemption.
In Celir LLP v. Bafna Motors, the Supreme Court held that under the amended provision, the borrower’s right of redemption ends once the auction notice is published. The judgment also made it clear that SARFAESI does not permit bank officials to act contrary to the law.
What Can the DRT Do?
When serious procedural or legal violations are proved, the DRT may:
- stay the proposed auction;
- stop confirmation of the sale;
- set aside the possession or auction notice;
- cancel an unlawful auction;
- order restoration of possession;
- direct the bank to obtain a fresh valuation; or
- require the bank to conduct a fresh auction according to law.
Act Quickly Before the Auction Is Completed
A property owner should not wait until the sale certificate is issued. A Section 17 application must generally be filed within 45 days of the relevant SARFAESI measure, along with an urgent interim application when the auction is approaching.
Financial hardship or a promise to pay later is usually not enough. A successful DRT challenge should identify a specific violation and support it with loan statements, payment receipts, notices, valuation reports, title documents and auction records.
This information is for general awareness and is not a substitute for advice based on the documents and facts of a particular case.
Important Judgments to Read
- ITC Limited v. Blue Coast Hotels Limited, 2018: Consideration of borrower objections and compliance with SARFAESI procedure.
- Mathew Varghese v. M. Amritha Kumar, 2014: Mandatory sale notice and protection against irregular property auctions.
- Celir LLP v. Bafna Motors, 2023: Borrower’s right of redemption and the legal finality of a valid auction.
- Agarwal Tracom Pvt. Ltd. v. Punjab National Bank, 2017: Scope of the remedy available before the DRT under Section 17.